12 April 2026 · Falah Mousa
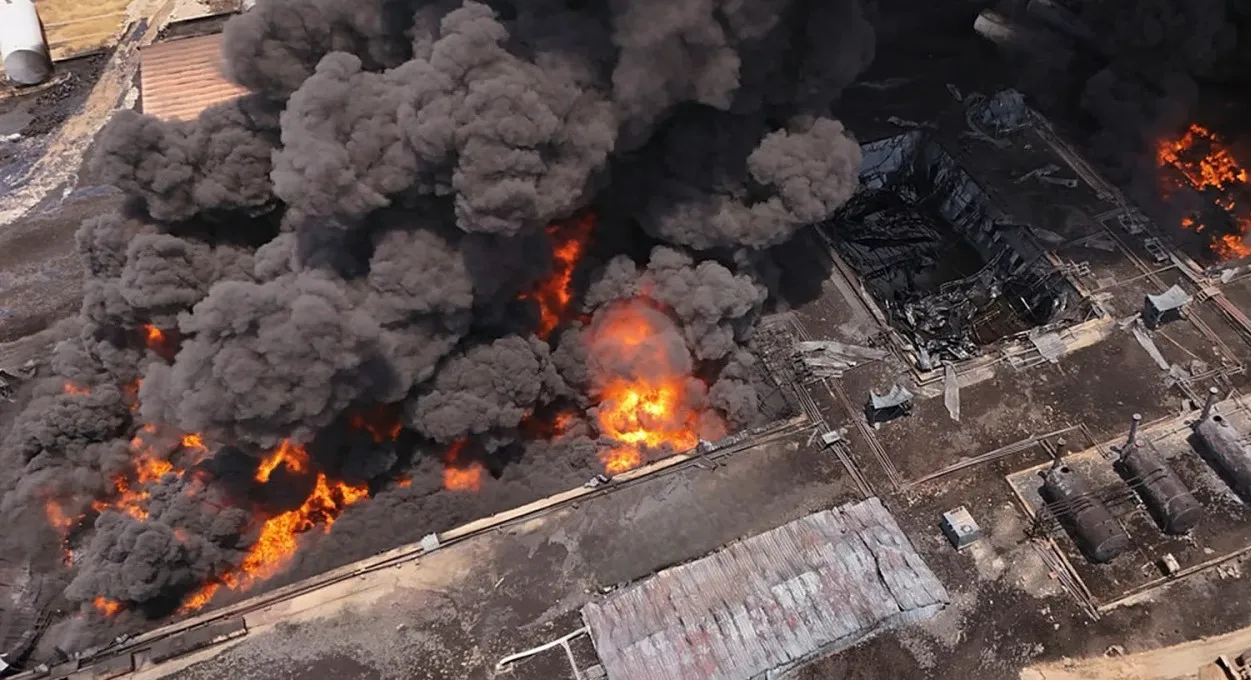
The actual energy crisis in the Gulf region is no longer the bombing itself. The bigger issue, and one that could last for many months, is the very costly effort to restore export capability, oil/gas production, and investor/producer confidence.
The global oil trading community is looking at Brent price movements; tanker movement; and the Strait of Hormuz. This is not where the global economic issue currently resides. The economic damage caused by American-Israeli war against Iran is due to damaged gas processing units, damaged refineries, damaged LNG trains; and years before they can be replaced. The current War in the Middle East has moved past how much higher prices will rise. A far greater concern is how much lost productive capability there will be for how long; and at what cost to a world economy that was already severely vulnerable to energy-related risks. Estimates suggest that restoring the ability of all energy facilities damaged during this conflict in the Middle East will require an estimated $25 billion or so. However, the real losses will occur as a result of lost exports; delayed investments; and lost capacity in areas previously considered stable.
The scale of the issue is evident from the example of Qatar. Losses to Ras Laffan have significantly reduced the ability to produce LNG. Because large frame gas turbines for such a purpose are manufactured by few producers who also have significant backlog orders for those products, recovering fully to pre-war levels may be many years away. Thus, in energy, capital is instantaneously available but a country cannot instantaneously manufacture specialized equipment or mobilize engineering personnel to safely restart production. That is why the economic consequences of war in the Gulf is going to be based on much narrower global supply chain networks for critical energy-related hardware rather than on how much capital wealth exists among producing nations.
That is when the direct loss due to physical destruction converts into a broader macro-economic shock. For every month of delayed delivery of LNG and/or crude oil, it creates tighter energy markets, alters global trade flows and increases the cost of energy well beyond the region. As a result, importers in both Asia and Europe are paying higher prices for their imported fuels, manufacturers are paying higher prices for their raw materials (feed stocks) and governments are facing additional rounds of upward inflation pressures at a time they are already carrying heavy debt burdens. The IMF’s warning that the US-Israel War on Iran will weigh on global growth reflects exactly this transmission mechanism: infrastructure damage in the Gulf does not stay in the Gulf.
The strategic lesson is bleak. For years Gulf producers believed that scale itself provided security. They built spare capacity, export terminals and giant downstream complexes on the assumption that large systems could absorb shocks. But resilience in hydrocarbons is not measured only in barrels a day. It lies in domestic maintenance capability, access to critical imported equipment, contractor depth and the political ability to keep shipping lanes open. The producer with the largest balance-sheet may not be the producer that restores output fastest.
The responsibility for this current crisis extends beyond the Iranian missile, drone attacks and acts of sabotage to take place throughout the region. It includes the actions of a White House which has used one of the world's most critical energy routes as a backdrop to unscripted statements, threatening language and brashness. In managing the conflict, the U.S. Administration has demonstrated alternate ultimatum and hasty tactical withdrawal styles; the U.S. has issued stern warnings regarding severe escalations followed by rapid moves toward an unstable cease-fire while restrictions on the Strait of Hormuz have remained in-place and broader terms of the war have yet to be resolved. This is not responsible statecraft; it is an irresponsible manner of managing crises that creates greater uncertainty among producers, buyers/importers, insurers and shippers. While nearly 20% of the world's normal oil trade passes through the Strait of Hormuz, when a country such as the United States demonstrates impulsive decision-making in regards to a matter of national strategic interest, that issue quickly evolves into a global economic shock to inflation, a global supply chain shock and a global loss of confidence.
European leaders are urging caution and negotiation; however, they continue to be extremely circumspect and fractured as well as generally politically timid (especially relative to their clear moral and strategic language regarding other conflicts). It would appear much of Europe does not want to engage in direct confrontation with Washington, due in part to concerns of creating a greater rift with President Donald Trump during a time of tenuous transatlantic relations. As such, we find ourselves familiarly mired in a crippling double-standard; where rhetoric concerning international order exists, yet Europe's reluctance to take action is based upon its continued reliance upon the same U.S. for security. That quietness has economic implications. It sends a signal to markets there is no defined Western plan for reducing escalation; nor is there a viable or serious political coalition in place to shield global energy trade from the unpredictable decisions made by Washington; nor is there a stable European counter-weight to Washington when it decides to confuse coercion theater with policy. Thus, this crisis can be viewed as the culmination of both conflict in the Gulf and political cowardice in Europe as well as the lack of discipline in Washington regarding strategy.
Iran, for its part, faces an even harsher reconstruction problem. Because of U.S.-led sanctions against Iran, fewer western-based contracting companies can operate in Iran. Thus, Iran has to rely more heavily upon Iranian (domestic) based companies and Chinese contractors for all aspects of the reconstruction process. While this approach could potentially ensure that repairs are made somewhat faster than if relying solely upon western contractors; it also limits Iran's ability to procure materials and equipment; limits the speed at which Iran can repair damaged infrastructure; and increases the likelihood that Iran will divert many of its limited resources away from new development projects toward restoring as much existing capacity as possible. This is where Iran finds itself currently. War-damaged assets in Iran are being destroyed by sanctions limiting the amount of international contractors available to restore those damaged assets.
Markets remain obsessed with the next shipping disruption or the next move in crude futures. They should spend more time on turbine lead times, engineering capacity and the fragility of post-strike reconstruction. The biggest cost of this war may not be the oil and gas the Middle East cannot produce today. It may be the energy the world assumed would come back soon, but will not.
Support Our Work
If you find our content valuable, please consider supporting our mission through a donation. Your contribution helps us continue providing high-quality analysis and insights.
Donation Options:
If you enjoy my work and would like to support it while helping me stay energized, I’d be deeply grateful for a coffee.
https://buymeacoffee.com/falahmousa
Thank you sincerely for your kindness and consideration.
 Falah Mousa
